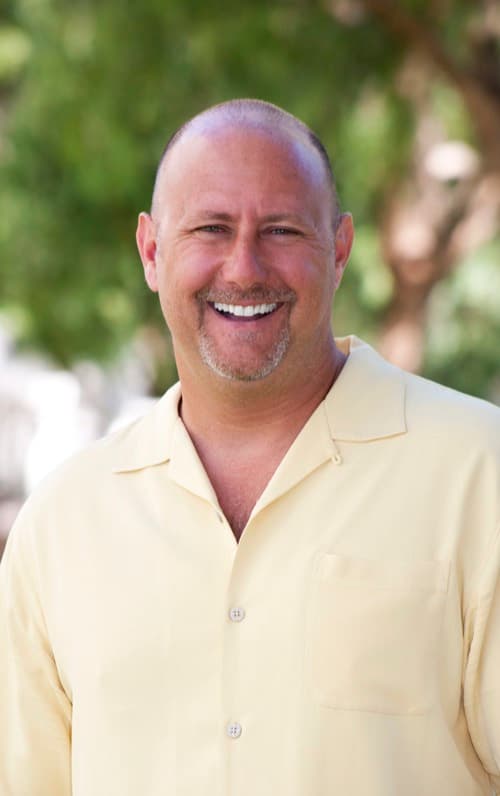
Rey Pasinli
Payments Engineer · 27 years · 85,000 merchants · ~250 banks, processors & PayFacs
Rey Pasinli is the payments engineer behind Total-Apps. He holds a B.S. in Mechanical Engineering from California State University, Fullerton, and an MBA from Pepperdine University, and began his career as a mechanical engineer on the International Space Station program before moving into e-commerce during the dot-com era.
Over 27 years he has worked directly with more than 85,000 merchants across roughly 250 banks, processors, ISOs, PayFacs, PSPs, and wallet solutions. He helped design fraud-scrubbing logic still used inside one of the industry's largest payment gateways, authored a 100-page compliance guideline covering CBD and peptide processing, and personally launched, secured approval for, and certified four separate PayFac licenses.
His approach treats payments as an engineering problem, not a sales problem: the right components, correctly matched to the business, built to hold under pressure. That perspective is why complex and high-risk merchants, the accounts most processors freeze or decline, come to Total-Apps to get placed and stay running.
Credentials
- B.S., Mechanical Engineering — California State University, Fullerton
- MBA — Pepperdine University
- Launched, secured approval for, and certified four separate PayFac licenses
- Authored a 100-page compliance guideline covering CBD and peptide processing
- Helped design fraud-scrubbing logic still used inside one of the industry's largest payment gateways
Areas of Expertise
- High-risk merchant underwriting
- Chargeback prevention & dispute resolution
- CBD, peptide & nutraceutical processing
- Reserve structures & processing limits
- PayFac licensing
- Split payments
- Card-network risk programs (VAMP, VIRP)
- Fraud scrubbing
- Payment gateway architecture
Rey writes and reviews the payment-processing guidance across the Total-Apps resource library and industry news.
Interviews & Podcasts
Rey is a regular guest on payments, e-commerce and direct-response shows. These are conversations about how merchant accounts actually work, from the underwriting side of the table.
Payments Experts PodcastPodcast2026
The Ugly Side of Merchant Processing: Fees, Reserves and Bad Contracts (Payments Experts Podcast, opens in a new tab)
With Christopher Dryden, Global Legal Law Firm
What separates a real payments partner from someone who just sells merchant accounts, with a payments attorney asking the questions.
Collaborators UnitePodcast2023
Optimizing Payment Processing and Your Merchant Accounts (Collaborators Unite, opens in a new tab)
The realities of e-commerce payments, and how merchants reduce risk to their own businesses.
Building Fortunes RadioPodcast
Visa Regulations and Drastic Changes for Merchant Accounts (Building Fortunes Radio, opens in a new tab)
With Peter Mingils
New Visa metrics threatening the merchant accounts of e-commerce and MLM companies, and what operators can do about them.
Enterprise Podcast NetworkPodcast
Total-Apps: Advanced Payment Processing Solutions (Enterprise Podcast Network, opens in a new tab)
Complex and high-risk payment processing, on the Top Entrepreneurs Podcast.
Challenge AssumptionsPodcast2016
Rey Pasinli on Social Commerce and Payments (Challenge Assumptions, opens in a new tab)
With Greg Davis
Evolving social commerce trends and the technology behind them.


On Video
Longer-form conversations on fraud, chargebacks and the card-network programs that decide who gets to process.
Success CirclesVideo2024
From Rocket Science to Ecommerce Mastery (Success Circles, opens in a new tab)
With Joseph Varghese
The route from aerospace engineering into payments, and what running 85,000 merchant accounts teaches you about leadership.

More on Rey’s YouTube channel (opens in a new tab).
Featured In
Profiles, features and interview transcripts covering the route from aerospace engineering into payments.
Success CirclesFeature
Rules for Success with Rey Pasinli (Success Circles, opens in a new tab)
From rocket scientist to e-commerce engineer: the route into payments.
Strategic ProfitsFeature
Rey Pasinli — Profile (Strategic Profits, opens in a new tab)
Profile covering Rey's background and specialisms.


Common Questions
The questions merchants ask Rey most often, answered plainly.
What makes a business “high-risk” in the first place?
Why do so many banks decline me without really looking?
What is the fastest way to get a frozen account resolved?
How low does my chargeback ratio need to be?
Do I really need more than one processing relationship?
What do you need from me to get started?
For Journalists & Podcast Hosts
Rey takes interview and commentary requests. He is an operator rather than a spokesperson, so the useful material is specifics: what acquirers actually check, why accounts get frozen, and how card-network rule changes land on real businesses.
Topics he covers:
- High-risk underwriting and why applications fail
- Chargebacks, disputes and card-network monitoring programs
- CBD, peptide and telehealth payment compliance
- Frozen funds, reserves and processing limits
- PayFac licensing and gateway architecture
Contact Your Total-Apps Team
From custom setup to improving performance to stopping business-critical problems, Total-Apps brings 27 years and 85,000 merchants of payments expertise to businesses across the United States.
Prefer to talk? Call us today:1-949-274-8975